




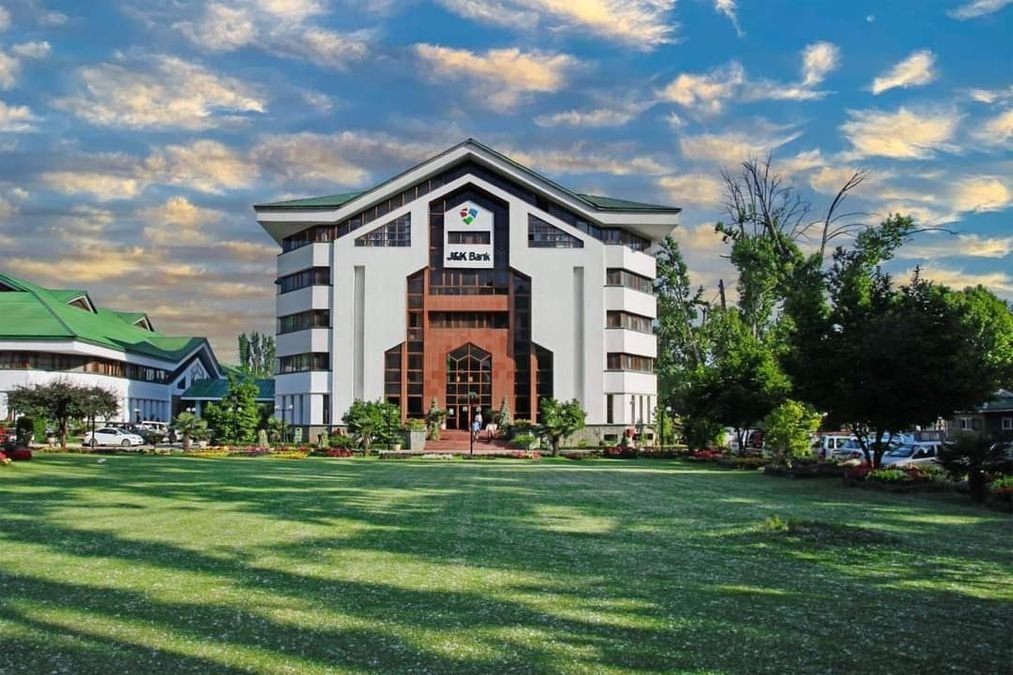
Srinagar, Oct 04: Jammu & Kashmir Bank has strengthened its risk-management architecture to deal with an increasingly complex banking environment, placing greater emphasis on credit quality, liquidity, fraud prevention, operational resilience, cybersecurity and emerging climate-related risks.
The bank’s Integrated Annual Report 2025-26, accessed by Rising Kashmir, shows that risk management is no longer confined to conventional financial risks, with the institution broadening its framework to include physical and transition risks arising from climate change, alongside environmental, social and governance concerns.
At the top of the structure, the Board of Directors sets the bank’s overall risk philosophy and appetite, while the Integrated Risk Management Committee oversees credit, operational, liquidity, market and Pillar II risks, including stress testing and the Internal Capital Adequacy Assessment Process.
“An independent Risk Management Vertical headed by the Chief Risk Officer is responsible for identifying, assessing, measuring, monitoring and mitigating risks. The framework is supported by specialised committees dealing with credit, market and operational risks, as well as the Asset Liability Committee,” the report reads.
It states that the Bank’s Board-approved Risk Appetite Framework establishes limits across credit, market, liquidity, operational, reputational, concentration and strategic risks, with risk considerations integrated into business planning and capital allocation.
“Credit risk remains a key area of focus, with the bank seeking to contain potential losses from borrower defaults through tighter underwriting, assessment of repayment capacity and cash flows, internal credit ratings and exposure limits,” the report reads. “Exposures are continuously monitored across sectors, products and borrower segments, while early-warning indicators and regular portfolio reviews are used to identify stress before it develops into larger asset-quality problems. Stress testing under adverse but plausible scenarios is also integrated with the bank’s capital adequacy assessment.”
The report states that liquidity and interest-rate risks are being managed through a Board-approved Asset Liability Management Policy, with the Asset Liability Committee regularly reviewing deposit and lending pricing, balance-sheet composition and compliance with prescribed limits.
“The Bank monitors liquidity through structural and dynamic liquidity statements, behavioural studies of deposits, and regulatory indicators including the Liquidity Coverage Ratio and Net Stable Funding Ratio,” the report reads, adding that “a contingency funding plan provides defined triggers and escalation mechanisms in the event of liquidity stress”.
It notes that the market risks arising from movements in interest rates, foreign exchange rates, equity prices and credit spreads are being controlled through exposure, duration, stop-loss and profit-and-loss limits. “The Bank also uses tools such as Value at Risk, modified duration, PV01, stress testing and scenario analysis to assess potential losses,” it reads. “Operational risk has received a similarly broad treatment, with the bank adopting a three-lines-of-defence model supported by risk and control self-assessments, key risk indicators, internal controls and independent assessments of new products, processes and outsourcing arrangements.”
The bank said it is also investing in technology, cybersecurity and system resilience, while maintaining business-continuity arrangements aligned with ISO 22301 and periodically testing disaster-recovery mechanisms.
“Fraud prevention forms another major pillar of the framework. A dedicated Fraud Risk Group under the Chief Risk Officer, real-time monitoring of digital transactions and analytics-based detection mechanisms are being used to identify suspicious activity and emerging fraud indicators,” it said.
According to the report, the bank is also tracking Red Flagged Accounts and conducting root-cause assessments of fraud cases to strengthen controls and prevent recurrence. Whistleblower and protected-disclosure mechanisms have been positioned as part of efforts to promote an ethical and risk-aware organisational culture.
“One of the emerging areas highlighted in the report is climate and ESG risk. The bank has initiated a phased ESG framework under which physical risks from extreme weather and longer-term climate shifts, as well as transition risks arising from policy, technology and market changes, will increasingly form part of its risk assessment,” the report adds. “Such risks could affect borrowers’ cash flows and collateral values, increase credit and operational losses and disrupt banking operations.”
The bank has adopted a Board-approved ESG Policy and undertaken an assessment of its existing practices against Indian and international sustainability and disclosure frameworks. “It is progressively integrating climate risks into credit appraisal, portfolio monitoring and enterprise risk assessment,” the report notes.


