




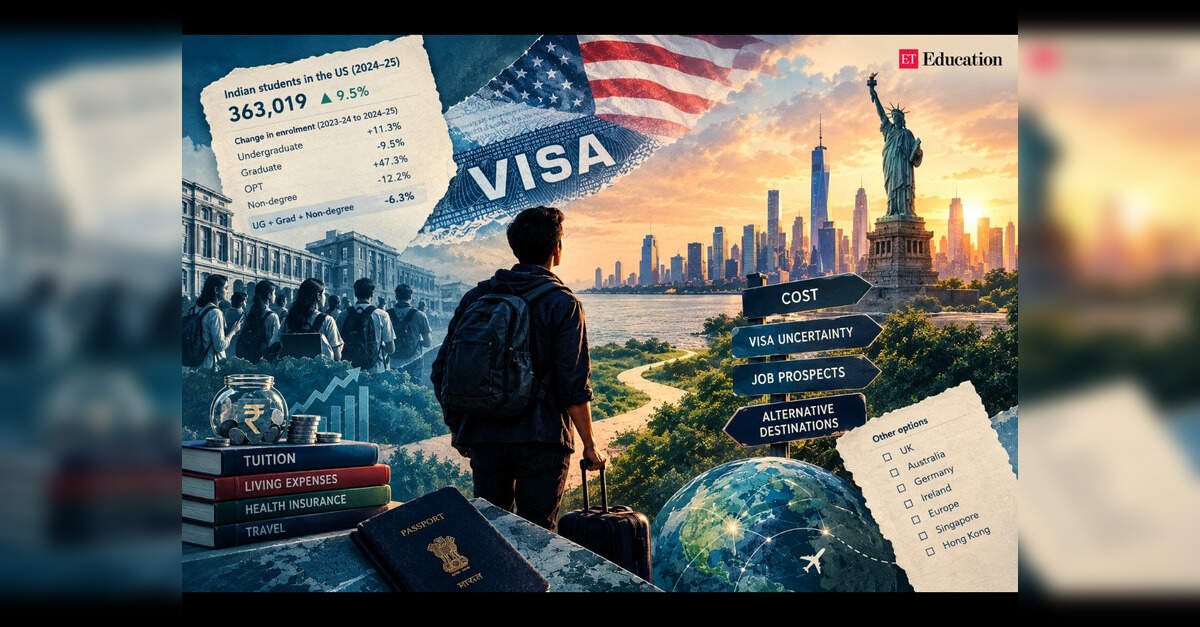
The United States continues to host more Indian students than any other country, but the headline growth in its Indian student population conceals a change in the composition of that population, and growing questions about the cost and return on investment of a US degree.
The number of Indian students in the US rose 9.5% to 363,019 in the 2024–25 academic year, from 331,602 a year earlier, according to the Institute of International Education’s Open Doors data. But graduate enrolment declined even as the number of Indian students participating in Optional Practical Training (OPT), which allows eligible international graduates to gain practical work experience in the US, rose sharply.
More recent indicators point to pressure on the pipeline of new students. IIE’s Fall 2025 Snapshot found that new international enrolments across reporting US institutions fell 17% from the previous fall. Separately, Common App reported a 15% decline in Indian applicants to its member institutions during the 2025–26 application season.
These figures measure different things: the overall population of Indian students already in the US, new enrolments at reporting institutions and applications to Common App member colleges. They cannot be treated as interchangeable measures, but together they raise questions about whether the growth in the overall student population will be sustained.
For Indian families, the decision increasingly involves more than securing admission. Tuition, living expenses, currency movements, visa uncertainty and the prospect of finding work after graduation all enter the calculation. For US universities, the implications extend to recruitment, enrolment conversion and the affordability of higher education for one of their largest international student markets.
The headline number hides a change in student mix
Open Doors data shows that the increase in India’s overall student population was accompanied by a contraction in the graduate category.
| Indian students in the US | 2023–24 | 2024–25 | Year-on-year change |
| Undergraduate | 36,053 | 40,135 | +11.3% |
| Graduate | 196,567 | 177,892 | -9.5% |
| Optional Practical Training (OPT) | 97,556 | 143,740 | +47.3% |
| Non-degree | 1,426 | 1,252 | -12.2% |
| Total | 331,602 | 363,019 | +9.5% |
| Undergraduate, graduate and non-degree combined | 234,046 | 219,279 | -6.3% |
Source: IIE Open Doors. Figures represent student-category headcounts, not new arrivals or verified numbers of full-fee-paying students.The table points to two simultaneous trends. The undergraduate population grew by 11.3%, but the graduate category contracted by nearly 19,000 students. Meanwhile, the number of Indian students in OPT increased by more than 46,000.
OPT is not a measure of new university enrolments. It captures students participating in practical training after or alongside the completion of their academic programmes, subject to the applicable rules. Its expansion helps explain how the overall Indian headcount can rise even as the combined number in undergraduate, graduate and non-degree categories falls.
The combined academic-category headcount declined from 234,046 to 219,279. This is a useful indicator of the changing composition of the Indian student population, but it should not be interpreted as a direct count of students paying tuition. The data does not identify individual fee payments, scholarships, assistantships or other funding arrangements.
Aman Singh, co-founder and CEO of GradRight, said the application trends seen on the platform suggested a difference between undergraduate and postgraduate demand. Undergraduate application volumes were broadly flat or up 1–3% year on year, while applications for master’s programmes, particularly computer science and data analytics, were down around 30–40% from their post-pandemic peak.
These are GradRight’s platform-level observations, not national application figures. They point to a possible difference in how prospective undergraduates and postgraduate students are weighing their options. For students choosing a master’s degree, the cost of the programme and the prospect of finding work after graduation can be central to the decision.
The figures should not be read as evidence that all postgraduate programmes are experiencing the same decline. Demand can vary by subject, institution, funding availability and career goals.
The next intake presents a separate challenge
The enrolment picture for the following academic year is more difficult.
IIE’s Fall 2025 Snapshot, based on responses from more than 825 US higher education institutions, found that new international enrolments, students attending their institution for the first time, fell 17% from fall 2024. Graduate enrolments declined 12%, while the number of international students in OPT increased 14%. The report also found that overall international student totals at reporting institutions fell 1%.
Among institutions reporting declines in new international enrolments, 96% cited visa application concerns and 68% cited travel restrictions as contributing factors. These percentages refer to institutions reporting declines in new international enrolments overall, not specifically to institutions with falling Indian enrolment.
The Common App’s end-of-season report, released in August 2026, provides another indicator from the undergraduate market. Indian applicants to Common App member institutions declined 15% in the 2025–26 application season. The report recorded a 10% decline in international applicants overall.
The Common App findings cover its member institutions, not every US university or every route through which Indian students apply. Even so, the figures suggest that the rise in the 2024–25 Indian student population should not be read as evidence that the pipeline of new students remains unaffected.
Ritu Sharma, Senior Director for South Asia at Acumen, part of Sannam S4, said students who had received offers and I-20 documents could still struggle to reach campus if they were unable to secure visa appointments or obtain visas in time. She said the impact was more pronounced at the postgraduate level than at the undergraduate level.
For universities, the distinction between admission and arrival is critical. An offer accepted by a student is not the same as an enrolment completed. Visa delays can disrupt travel plans and course starts even after institutions have invested in recruitment and admissions.
The latest indicators do not, however, establish that visa policy alone caused the change in demand. Cost, exchange rates, employment prospects and competition from other destinations also influence students’ decisions. The decline in new enrolments should therefore be read alongside the broader changes in demand, rather than attributed to one policy measure.
A US degree can require ₹45–65 lakh in the first year
Affordability remains central to the decision. Tuition varies substantially by institution and programme, but annual fees can run into tens of thousands of dollars before living expenses are added.
GradRight’s estimates put annual tuition at $25,000–$40,000 for undergraduate study at public universities and $35,000–$50,000 at private institutions. For master’s programmes, the estimates range from $15,000–$35,000 at public universities to $35,000–$60,000 at private universities. MBA tuition can be higher still.
| Programme and institution type | Indicative annual tuition (USD) |
|---|---|
| Undergraduate, public university | $25,000–$40,000 |
| Undergraduate, private university | $35,000–$50,000 |
| Master’s, public university | $15,000–$35,000 |
| Master’s, private university | $35,000–$60,000 |
| MBA | $60,000–$75,000 |
Suggested note below the table: These are indicative annual tuition estimates, not total costs of attendance. Living expenses, health insurance, travel and other fees may add substantially to the overall cost. Actual tuition varies by institution and programme.
A separate benchmark from the College Board puts average published tuition and fees for 2025–26 at $31,880 for out-of-state students at public four-year colleges and $45,000 at private nonprofit four-year colleges. These figures cover tuition and fees, not the full cost of attendance.
Once housing, food, health insurance, travel and other expenses are included, the total rises considerably. GradRight estimates that undergraduate students may spend 12,000–20,000 annually on housing and food, in addition to 1,500–3,000 for health insurance. For master’s students, living expenses and insurance together can amount to roughly 15,000–20,000 a year.
Based on these estimates, the first-year budget for a STEM master’s programme can reach ₹45–65 lakh. A private undergraduate programme or MBA may cost ₹70–85 lakh, while the annual cost at some top private undergraduate institutions can approach ₹90 lakh to ₹1 crore, according to estimates shared by education advisers. Actual costs depend on the institution, course, duration, financial aid and exchange rate.
Akshay Maliwal, founder and CEO of AddedEducation, said the US remained a first choice for many affluent undergraduate families, particularly those targeting selective institutions. For families funding education largely from savings, currency movements alone might not be enough to change the decision, but they could prompt closer scrutiny of the value offered by a programme.
The financial pressure is not limited to the first year. Families need to consider the cost across the full duration of a degree, including possible annual increases, the conditions attached to financial aid and the time required to secure employment after graduation.
A weaker rupee raises the cost and repayment risk
The cost of studying in the US is dollar-denominated, while most Indian families earn and save in rupees. When the rupee weakens, the amount required to fund the same dollar expense rises, even if the university has not increased its fees.
For families using education loans, that can affect the size of the borrowing requirement and the rupee amount needed to meet tuition instalments and living expenses. For those self-funding a degree, it can mean drawing down a larger share of savings than originally planned.
Sagar Bahadur, Senior Vice President – Strategic Partnerships & Growth at Manifest Global, said families should account for currency fluctuations and the possibility that a graduate may take longer than expected to find a job.
“Families need to plan for the full duration of the programme, allow for currency fluctuations and assess repayment against realistic career outcomes,” Bahadur said. “An overseas degree can be an excellent investment, but the financial plan should work even if a student takes longer than expected to find a job.”
That concern connects affordability with employment prospects. A degree may offer strong academic or professional opportunities, but a family taking on a large loan must also consider the timing and level of future earnings. If employment is delayed, repayment obligations remain even as the expected financial return takes longer to materialise.
Singh said financing was a significant part of the overseas education decision. GradRight estimates that a substantial share of students’ total expenses is financed through loans, with some lenders offering funding that can cover much of the cost of attendance. The platform has estimated that education loans typically finance around 70–80% of total expenses for the students it tracks, though this should not be treated as a national figure. Actual borrowing varies by family, lender, institution and course.
Singh also pointed to the role of scholarships and institutional aid in determining what students ultimately pay. Some public universities offer scholarships in the range of 5,000–15,000, according to GradRight’s estimates, while financial support at private institutions can vary considerably. The headline tuition fee therefore does not necessarily represent the net cost for every student.
For families comparing offers, the relevant calculation is the total amount they will actually need to fund, after aid, over the duration of the programme — not simply the first-year tuition figure.
The tuition opportunity is substantial, but actual revenue is unknown
The scale of Indian enrolment makes the financial stakes significant, but estimating university tuition revenue requires care. Open Doors provides student counts, not a consolidated account of tuition collected from Indian students.
ET Education has modelled the potential gross annual tuition value of the 219,279 Indian students recorded in undergraduate, graduate and non-degree categories in 2024–25. Applying an assumed annual tuition range of $28,000–$42,000 produces a gross estimate of approximately $6.1billion–$9.2 billion, with a midpoint of about $7.7 billion.
At an illustrative exchange rate of ₹95 to the dollar, this would be equivalent to roughly ₹58,000 crore–₹87,500 crore.
This is an illustrative model, not a measure of actual university revenue. The 28,000–42,000 tuition assumption is not a verified weighted average for Indian students. The calculation does not account for differences in programme length, students paying lower rates, scholarships, assistantships, fee waivers or other funding arrangements. It also excludes the OPT category and does not estimate students’ wider spending on accommodation, food, transport or other services.
The estimate therefore illustrates the potential scale of tuition associated with the academic-category headcount; it should not be interpreted as money actually received by US universities. A reliable revenue estimate would require institution-level enrolment and net-tuition data, along with information on the funding arrangements applicable to Indian students.
Even with these limitations, the exercise illustrates why international recruitment matters to US higher education. Changes in the number of students arriving, the programmes they choose or the financial aid they receive can affect institutional finances, although the impact will vary substantially across universities.
For Indian families, the same figures show the scale of the financial commitment involved. The cost of a US degree is not just an individual household decision; it is also a major cross-border education expenditure whose value depends on academic outcomes, funding and employment opportunities.
Return on investment is becoming more important
The value proposition of a US degree has traditionally combined academic reputation, access to specialised programmes, professional networks and the opportunity to gain work experience after graduation. For many students, the employment pathway is part of the financial calculation, not an afterthought.
That pathway is now a more uncertain part of the proposition. Students must weigh the cost of a degree against the likelihood of finding relevant work, the time available to gain experience and the immigration rules governing what happens after graduation.
Sharma said employment outcomes and long-term return on investment were important considerations in students’ decisions. Acumen’s 2026 Agent Perception Survey found that 89% of surveyed agents identified employment outcomes and long-term ROI as key drivers. This is a survey of agents’ perceptions, not a direct survey of all students or families; its sample size and fieldwork details would be needed to assess how broadly the finding can be generalised.
The proposed OPT fee rule adds another layer of uncertainty. Published in October 2026, the proposal would require Student and Exchange Visitor Program-certified institutions to pay $70,000 for an initial OPT recommendation and $30,000 for a subsequent recommendation for an F-1 student. The proposal is not in effect. Under the proposal, the fees would be paid by institutions, rather than directly charged to students, although any eventual financial consequences for institutions and students remain uncertain.
For students considering expensive STEM programmes, where the prospect of post-study work can be an important part of the return-on-investment calculation, uncertainty over OPT is particularly relevant. The proposal should not, however, be treated as an existing cost that students must already pay, or as evidence that every university will pass such a cost on to them.
For universities, the implication is that rankings and reputation may not be sufficient on their own. Students and families increasingly need a credible account of the total cost, available financial aid, programme outcomes and the practical route from graduation to employment.
Alternative destinations are entering the conversation earlier
The competition for Indian students is not simply a contest between the US and one other country. Students compare programme quality, tuition, scholarships, work opportunities, visa processes and the ability to remain in a destination after graduation.
Bahadur said the US was facing stronger competition for Indian students than it had a few years ago. The UK, Australia, Germany, Ireland and other European destinations were relevant alternatives, depending on the programme and the student’s goals. He cautioned, however, against interpreting increased consideration of these destinations as proof that they had gained market share; that would require comparable application and enrolment data.
Maliwal said the UK was the most prominent alternative among the families served by AddedEducation, with Europe, Singapore and Hong Kong also being considered. His observations reflect the families his organisation works with, rather than the choices of all Indian students.
GradRight has also reported increased application activity for Germany and Australia on its platform, citing a 73% rise for Germany and an 11% increase for Australia over a comparison period. Those figures are platform-specific, and the comparison period and definition of an application should be established before they are used to quantify a change in destination demand. An increase in applications does not automatically translate into higher enrolment.
The distinction matters because a student considering several countries is not necessarily abandoning the US. Families may apply to multiple destinations to preserve their options if costs rise, visa decisions are delayed or the employment outlook changes. Whether this translates into a sustained shift in actual enrolments will depend on admissions outcomes, affordability, visa rules and programme-level choices.
For some undergraduate families, the US remains attractive because of the range of institutions and programmes available. For postgraduate students weighing tuition against the prospect of employment, differences in cost and post-study pathways may carry greater weight. Neither pattern should be assumed to apply uniformly across all students.
A more selective market, not an overnight exit
The latest data does not show that Indian students have abandoned the US. India remains the leading source country for international students there, and the overall Indian headcount reached 363,019 in 2024–25. Undergraduate enrolment in that year also increased.
What the figures show is that the overall headcount is an incomplete measure of the market. Graduate numbers have fallen, the OPT population has expanded, new international enrolments weakened in fall 2025 and Indian applications to Common App member institutions declined in the 2025–26 season.
The expert assessments add context to those shifts. GradRight’s platform data points to a difference between undergraduate and postgraduate demand. Acumen highlights the risk that visa delays can prevent admitted students from reaching campus. Manifest Global links affordability with currency risk and the uncertainty of post-study employment. AddedEducation’s observations suggest that some families continue to prioritise the US while comparing more alternatives earlier in the process.
These perspectives do not establish a single cause for the changing student flows. Instead, they point to a decision shaped by several connected factors: the quality and cost of a programme, access to funding, the likelihood of arriving in time for the academic year, and the employment prospects that help determine whether the investment can be justified.
For US universities, the challenge is to convert admitted students into actual enrolments while addressing questions about affordability, visa timing and employment outcomes. For Indian students and families, the calculation is becoming more detailed: not simply whether a US degree is desirable, but whether its total cost and expected outcomes justify the risk.
The next test will be whether the decline in new enrolments and Indian undergraduate applications persists, and whether it translates into a sustained change in where Indian students choose to study. Until comparable data on applications, visa issuance and actual enrolment is available across destinations, claims of a wholesale shift away from the US would be premature.
For now, the evidence points to a market under pressure and a more demanding question for universities competing for Indian students: can they make the academic and employment value of a US degree sufficiently clear to justify its cost and uncertainty?


