




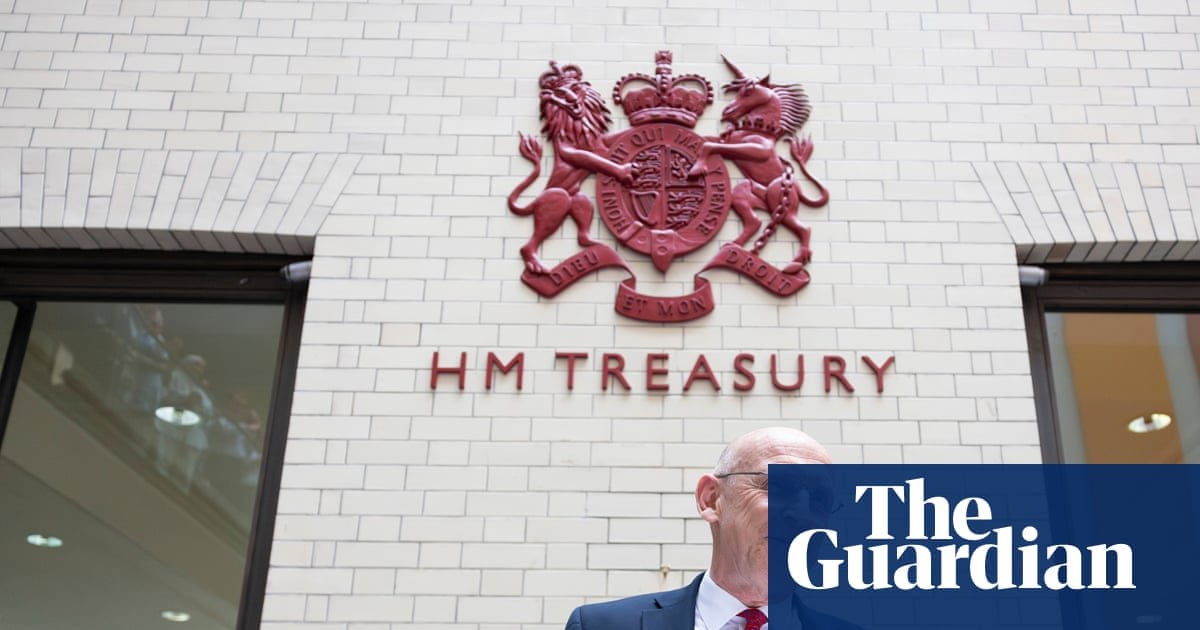
The Treasury ran a higher than expected budget deficit of £24.5bn last month as rising inflation pushed up the interest paid on government debt, increasing pressure on John Healey before his first budget next Wednesday.
Official figures show the government paid £10.9bn in debt interest: the highest September figure since records began, and only the eighth time the monthly number has been above £10bn.
Some government bonds are directly linked to the retail prices index measure of inflation, with payments rising in line with it. RPI has increased in recent months as the Iran war has pushed up energy costs. The Office for National Statistics said this had added £4bn to debt interest costs in September alone.
Total government debt is estimated to have hit £3tn for the first time – although as a share of the size of the economy it has fallen to 94%, from 95% a year ago.
The £24.5bn monthly deficit on the public finances was up from £17bn in August, and £1.9bn higher than the independent Office for Budget Responsibility had forecast.
In the financial year so far, public sector net borrowing is £97.8bn, the ONS said – £4.4bn lower than last year but still £6bn higher than the OBR expected.
The data underlines the impact of the Iran war on the public finances, before next Wednesday’s budget.
Healey has been keen to stress his determination to stay within the fiscal rules set out by his predecessor as chancellor, Rachel Reeves.
However, he is widely expected to accept a slimmer financial buffer, or “headroom”, against those rules than the £24bn Reeves had built up at the time of her spring forecast.
after newsletter promotion
Higher inflation tends to be good for tax revenues but it also squeezes how much government departments can achieve within fixed budgets.


