

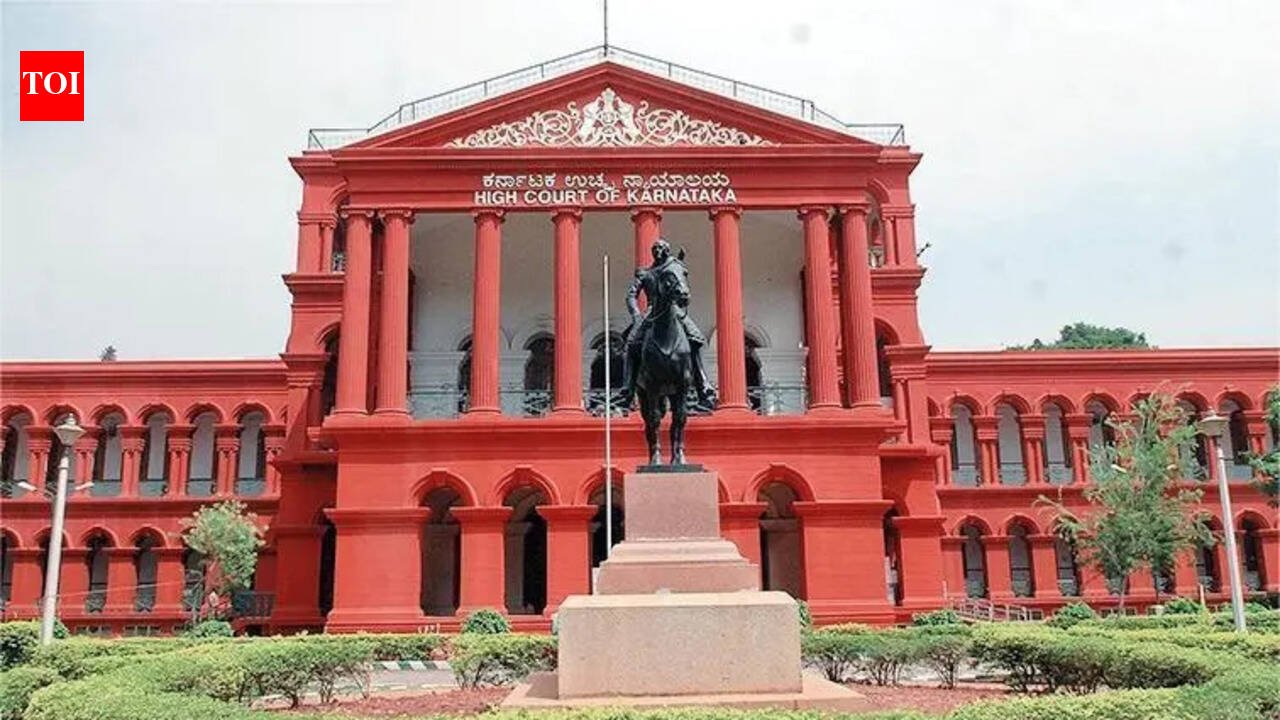
Bengaluru: Karnataka high court has reaffirmed a land parcel at Sonnappanahalli village in north Bengaluru, being used by Indian Air Force (IAF), as defence land.The land – 3 acres and 12 guntas – acquired by the govt during World War II in 1943, when India was under British rule, had remained part of the IAF establishment for decades.A division bench of the high court has now overturned a single judge’s order that had allowed a private party’s claim over the property, upholding the position upheld by revenue authorities.The division bench of Justices DK Singh and H Shanthi Bhushan observed that land forming part of an operational IAF facility could not be treated like an ordinary parcel of private agricultural land. An aircraft taxi track is integral to airbase operations, facilitating movement within the station and connecting different operational areas of the airfield.The dispute reached the division bench after a single judge, in July 2026, allowed the claimant’s petition and quashed concurrent orders of the assistant commissioner and deputy commissioner. Both revenue authorities had held that the land was part of the property acquired for ministry of defence (MoD). The ministry challenged the single judge’s decision.Examining the historical records, the division bench found that documents dating back to the British era established the land’s acquisition for defence purposes. These included a May 31, 1943, letter from the surveyor to the special land acquisition officer, a survey report dated Feb 26, 1944, compensation records, the village map and Military Land Register.The court noted that the original landowner had been paid compensation following the acquisition.Emphasising the significance of Military Land Register, the bench said it was an official and conclusive document in matters concerning defence land. It added that when land forms part of an operational military facility, its identity and use should be assessed in the light of defence records and the purpose for which it was acquired, rather than merely on the basis of subsequent private transactions or entries relied upon by individuals.
