


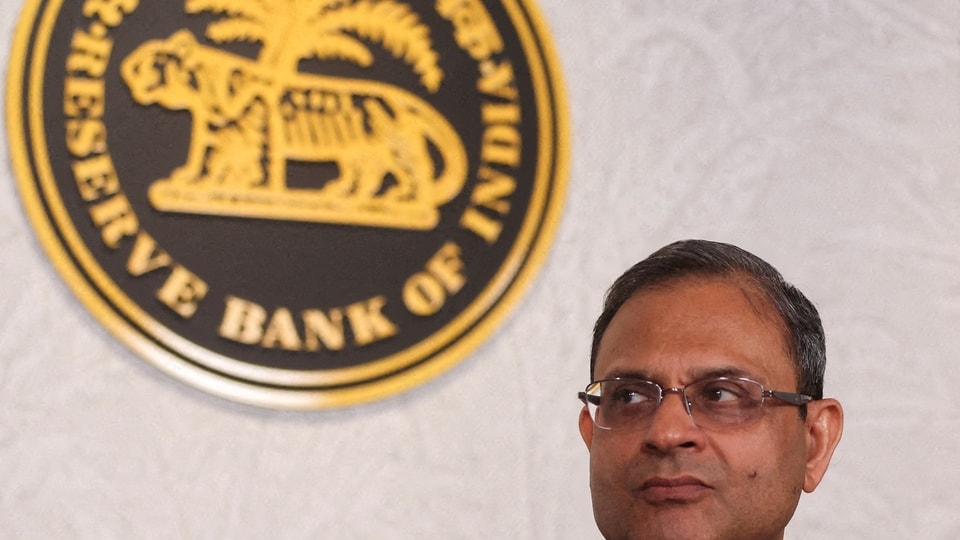
The Reserve Bank of India (RBI) on October 7 raised its policy repo rate by 25 basis points to 5.50%, after almost three-and-a-half years, amid inflationary pressures and continuing geopolitical tensions arising from the West Asia crisis. The rate hike could make new home loans expensive and push up EMIs for existing floating-rate borrowers, depending on how lenders transmit the increase.
The decision by the Monetary Policy Committee (MPC) marks a shift from its August policy, when it kept the repo rate unchanged at 5.25% and retained a neutral stance while seeking greater clarity on the inflation outlook and the balance between growth and inflation.
In his statement, RBI Governor Sanjay Malhotra said, “After a detailed assessment of the evolving macroeconomic and financial conditions, developments and the outlook, the MPC voted unanimously to increase the policy repo rate by 25 basis points.”
What does it mean for your EMI?
Following the rate hike, borrowers could see an increase in their monthly home-loan outgo, depending on how the increase is transmitted by lenders.
Consider a ₹50 lakh home loan for 20 years at 7.15%.
According to Raoul Kapoor, co-CEO, Andromeda Sales and Distribution, the RBI’s 25-basis-point repo rate hike is expected to have a marginal impact on home-loan EMIs.
“The RBI’s decision to increase the repo rate by 25 basis points is broadly in line with market expectations, given the prevailing global uncertainties, inflationary pressures, rising bond yields, a depreciating rupee and continuing geopolitical tensions in West Asia,” he said.
The rate hike is likely to put some upward pressure on retail lending rates, including home loans, car loans and personal loans. However, the impact on borrowers is expected to remain marginal, particularly as home-loan interest rates are currently at relatively attractive levels. Home-loan rates are currently available from around 7.15% for eligible borrowers.
If the entire 25-basis-point increase is passed on to borrowers, a home-loan rate of 7.15% could rise to around 7.40%. For a borrower with a ₹50 lakh home loan for 20 years, this would mean an estimated increase of around ₹759 in the monthly EMI. For a ₹1 crore loan, the increase would be around ₹1,516 per month, he explains.
Also Read: RBI raises repo rate by 25 points in first hike in four years, loan EMIs may rise
The actual impact may vary depending on the lender, loan benchmark, borrower profile and whether the rate increase is adjusted through a higher EMI, a longer tenure, or a combination of both, Kapoor added.
The Reserve Bank of India’s 25-basis-point repo rate hike marks the start of an upward monetary cycle, meaning borrowing costs will likely face upward pressure in the near terms. Over a typical 15- to 20-year housing loan tenure, however, rate cycles are inevitable; borrowers should expect to navigate at least two to three complete phases of tightening and easing, explains Renu Maheshwari, SEBI Registered Investment Advisor, Finscholarz.
A home purchase should primarily hinge on your personal life timeline, genuine housing needs, and broader financial goals—not transient interest-rate movements. While rising EMIs undoubtedly reduce immediate affordability, this volatility is precisely the buffer that should be engineered into long-term financial planning so life goals remain intact, she says.
“Cash flow pressure is more pronounced during the initial 5 years of a mortgage. This up-cycle, combined with real estate prices that have already peaked over the past few years, could dent buyer sentiment and dampen demand in mass-market housing. Before committing to a long-term loan, prospective buyers should work with a fee only financial planner to stress-test their cash flows over a 5- to 10-year horizon and ensure adequate repayment buffers,” she adds.
What should home-loan borrowers do?
Borrowers should not rush to prepay their entire home loan solely because of a 25-basis-point rate hike. Instead, they should first check the interest rate currently being charged, the remaining loan tenure and whether the loan is linked to the repo rate or another benchmark, say personal finance experts.
“They should also review the spread charged by the lender and check whether any prepayment charges apply before making a large payment. Borrowers can also compare balance-transfer offers from other lenders to determine whether switching can help reduce their effective interest rate and overall interest outgo,” Kapoor said.
