

For real estate developers, an initial public offering is no longer simply a question of raising money. It is a decision that can change the way a company operates, brings in talent, builds credibility and manages its business.
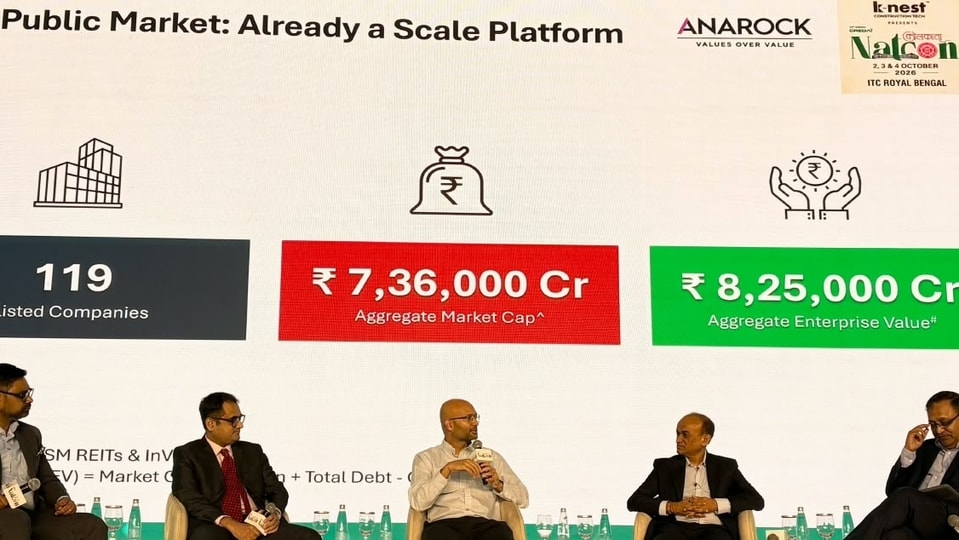
That was the central question at a session on IPOs at CREDAI NATCON 2026, the three-day national real estate convention being held in Kolkata from October 2 to 4.
With India’s primary market seeing strong activity this year, the discussion focused on a more fundamental issue for developers: should a company go public because market conditions are favourable, or only when the business is ready for the discipline and scrutiny of a listed company?
The timing of the discussion is significant. India’s IPO market has remained highly active in 2026. September alone saw 34 IPOs raise nearly ₹39,340 crore, while the pipeline as of September 25 comprised 237 companies seeking to raise an estimated ₹4.48 lakh crore, as per data shared by the speakers during the panel discussion.
At the same time, the real estate sector has been more cautious. Several developers have reconsidered or delayed IPO plans amid a moderation in housing demand and changing market sentiment, even as commercial real estate has remained comparatively resilient.
Against this backdrop, Shobhit Agarwal, MD & CEO, ANAROCK Capital Advisors, Varun Gupta, Director, Ashiana Housing Ltd, Deepak Kishan Goradia Chairman & MD, Dosti Realty , Abhimanyu Bhattacharya Partner, Capital Markets, Khaitan & Co, and Pinak Rudra Bhattacharyya Senior Vice President & Head – Corporate Finance, IIFL Capital discussed what an IPO actually means for a developer.
IPO is not just about raising money
Agarwal described an IPO as a significant business milestone rather than a one-time fundraising exercise. For a developer, the benefits extend beyond the immediate cash raised.
His argument was that a listed company’s shares themselves become a form of currency, giving the business another instrument with which to raise capital, structure transactions and build value.
An IPO can therefore provide three broad advantages: access to capital, a publicly traded equity currency and greater visibility.
For a real estate company, access to capital is particularly important because development is inherently capital intensive. Projects require large upfront investments, while land acquisition, construction and project delivery operate over long cycles.
But the decision to list also brings a different level of scrutiny.
Listing changes the way a company operates
Varun Gupta said the benefits of becoming a listed company go beyond the money raised through the IPO.
“Listing not only helped to buy” was part of his observation on the wider benefits of accessing the public markets, with the discussion highlighting access to capital and institutional investors such as insurance companies.
For Gupta, the compliance requirements associated with listing can also bring discipline to a business.
He compared the process to having a fitness trainer in a gym: the requirement to maintain documents, systems and financial information and to have the company’s performance reviewed regularly can force a business to become more organised.
For developers, this discipline can have significance because a listed company is required to operate with greater transparency, with financial performance and other material information subject to regular disclosure and scrutiny.
‘There is no right time’
Agarwal’s message to developers considering an IPO was that there is no universal “right time” to list.
The more important question, he said, is whether the company is ready.
An IPO cannot be treated as a one-day event. A developer first has to build a sustainable business and then demonstrate that it is capable of meeting the requirements of the public market.
The preparation itself can improve the company, according to the discussion. Developers need to prepare well in advance, put systems in place and ideally operate the business as if it were already listed.
That means strengthening financial reporting, governance, documentation, internal processes and management systems before approaching the market.
Preparation starts long before the IPO
The session also underlined that an IPO is effectively a journey rather than a single transaction.
A developer contemplating a listing has to prepare for greater transparency, investor scrutiny, quarterly reporting and continuous engagement with shareholders. The company’s business model, project pipeline, financial performance and governance systems all come under a much closer lens.
The preparation, therefore, is not merely about meeting regulatory requirements. It can become a process of making the underlying business stronger and more institutional.
The speakers also emphasised the importance of setting realistic expectations. For a company going public, the principle is to under-promise and then deliver, rather than build expectations that the business cannot sustain.
Also Read: Dosti Realty, Moneytree Realty file IPO papers with Sebi through confidential route
IPO market is strong, but real estate cannot ignore the cycle
The debate comes at a time when the broader Indian IPO market is showing considerable strength. In the first half of FY27, companies raised a record more than ₹1 lakh crore through IPOs, supported by domestic liquidity and strong investor participation.
However, the real estate sector has not moved in lockstep with the broader IPO market. several developers were rethinking listing plans as housing demand moderated and investor sentiment became more selective.
That makes preparedness particularly important for developers. A strong primary market does not automatically mean that every real estate company should rush to list.
The question is whether the business is sufficiently mature, transparent and financially prepared to live with the obligations of being a public company.
For Agarwal, the IPO opportunity is effectively a once-in-a-lifetime milestone for many businesses. But the preparation for that opportunity begins much before the listing documents are filed.
For Gupta, the value of listing extends beyond the initial capital raise. Access to institutional capital, greater visibility and the discipline imposed by compliance can fundamentally change the way a company operates.
The message emerging from the NATCON discussion was therefore less about whether developers should launch an IPO now and more about whether they are ready for what comes after the IPO.
In a market where capital is available but investor scrutiny is rising, the listing may be the event that lasts one day. Building a company capable of living as a listed entity is the much longer journey.
